Getting a Mortgage Shouldn’t Be Stressful—We Can Help

Tyler Trompetter • July 23, 2026

Buying a Home? Follow These 6 Key Steps for a Smooth Experience

Buying a home is likely one of the biggest financial decisions you’ll ever make. It’s exciting—but it can also be overwhelming, especially when it comes to understanding how mortgage financing works.


To help make the process smoother (and far less stressful), here are six essential steps every homebuyer should follow:


1. Start With a Mortgage Professional—Not MLS

It’s tempting to start your home search by scrolling through listings and booking showings—but the real first step should be speaking with an independent mortgage professional.


Unlike a bank that offers only one set of products, an independent mortgage expert has access to multiple lenders and options. That means better advice, better rates, and a better chance of finding a mortgage that truly fits your needs.


2. Build a Personalized Mortgage Plan

Unless you’re buying your home with cash, you’ll need a solid financing strategy. That means:

  • Reviewing your credit score
  • Running affordability calculations
  • Exploring different mortgage types, terms, and features
  • Understanding down payments and closing costs

The sooner you start planning, the more confident you’ll feel. Don’t wait until you’ve found the “perfect” property—get ahead of the process now.


3. Figure Out What You Can Actually Afford

What a lender says you can borrow doesn’t always match what you can comfortably pay each month.

Take a close look at your budget, lifestyle, and spending habits. Think about how your mortgage payments, property taxes, utilities, and other costs will fit into your everyday cash flow.

Avoid the stress of being house-poor by knowing your real-life affordability, not just your paper pre-approval.


4. Get Pre-Approved the Right Way

A true mortgage pre-approval isn’t just entering numbers into an online calculator. It means:

  • Completing a mortgage application
  • Submitting all your required documentation
  • Having a mortgage professional fully assess your file

When you’re officially pre-approved, you’ll shop for homes with confidence, knowing what you qualify for and that you’re financially ready.


5. Submit Your Documents Promptly and Stay Flexible

Once you find a property and your offer is accepted, time is of the essence. That’s when all the upfront work you’ve done really pays off.

Be ready to:

  • Provide additional documentation if requested
  • Respond to your mortgage professional quickly
  • Stay flexible and proactive throughout the approval process

Your lender needs to verify everything before finalizing the loan, so staying organized is key.


6. Don’t Make Big Financial Changes Before Closing

Once you’ve secured financing and waived your conditions, freeze your finances until after you get the keys.

Seriously—don’t:

  • Change jobs
  • Apply for new credit
  • Take out a loan
  • Make a large withdrawal


Even small changes can throw off your approval. Keep everything status quo until you officially take possession.


Recap: 6 Steps to a Smooth Home Purchase

  1. Connect with an independent mortgage professional
  2. Create a mortgage plan early
  3. Know what you can afford (not just what you qualify for)
  4. Get fully pre-approved
  5. Stay on top of documentation
  6. Avoid major financial changes before possession


Ready to Buy with Confidence?

If you’re thinking about buying a home—or just want to know what’s possible—let’s talk. I’ll help you map out a personalized plan that makes your homebuying journey feel simple, strategic, and stress-free.

Reach out anytime. I’d love to help you get started.
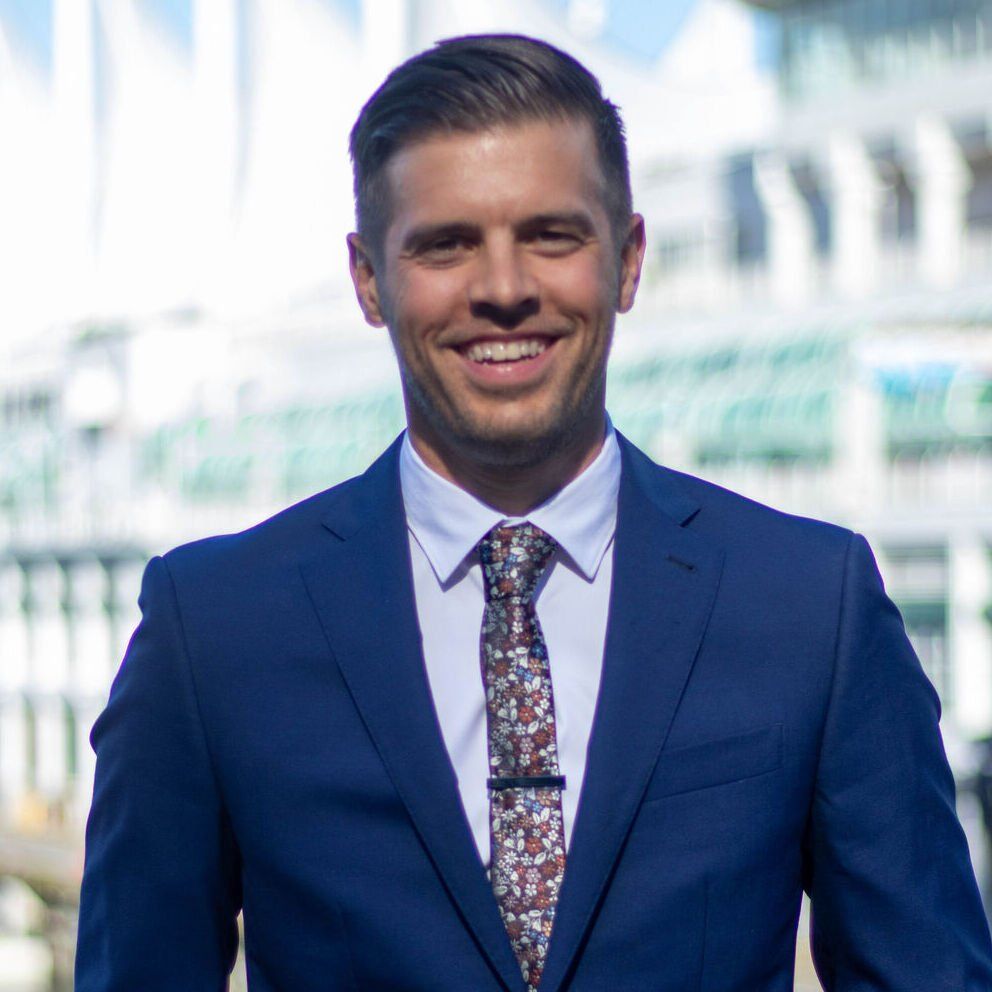

TYLER TROMPETTER
Mortgage Professional

Call Me Email Me

Recent Posts

By Tyler Trompetter • October 15, 2026
Owning a home feels great—carrying a large mortgage, not so much. The good news? With the right strategies, you can shorten your amortization, save thousands in interest, and become mortgage-free sooner than you think. Here are four proven ways to make it happen: 1. Switch to Accelerated Payments One of the simplest ways to reduce your mortgage faster is by moving from monthly payments to accelerated bi-weekly payments . Instead of 12 monthly payments a year, you’ll make 26 half-payments. That works out to the equivalent of one extra monthly payment each year, shaving years off your mortgage—often without you noticing much difference in your budget. 2. Increase Your Regular Payments Most mortgages allow you to boost your regular payment by 10–25%. Some even let you double up payments occasionally. Every extra dollar goes directly toward your principal, which means less interest and faster progress toward paying off your balance. 3. Make Lump-Sum Payments Depending on your lender, you may be able to make lump-sum payments of 10–25% of your original mortgage balance each year. This option is ideal if you receive a bonus, inheritance, or other windfall. Applying a lump sum directly to your principal immediately reduces the interest charged for the rest of your term. 4. Review Your Mortgage Annually It’s easy to put your mortgage on auto-pilot, but a yearly review keeps you in control. By sitting down with an independent mortgage professional, you can check if refinancing, restructuring, or adjusting terms could save you money. A quick annual review helps ensure your mortgage is always working for you—not against you. The Bottom Line Paying off your mortgage early doesn’t require a massive lifestyle change—it’s about making smart, consistent choices. Whether it’s accelerated payments, lump sums, or regular reviews, every step you take helps reduce your debt faster. If you’d like to explore strategies tailored to your situation—or want a free annual mortgage review—let’s connect. I’d be happy to help you find the fastest path to mortgage freedom.
By Tyler Trompetter • October 1, 2026
Co-Signing a Mortgage in Canada: Pros, Cons & What to Expect Thinking about co-signing a mortgage? On the surface, it might seem like a simple way to help someone you care about achieve homeownership. But before you sign on the dotted line, it’s important to understand exactly what co-signing means—for them and for you. You’re Fully Responsible When you co-sign, your name is on the mortgage—and that makes you just as responsible as the primary borrower. If payments are missed, the lender won’t only go after them; they’ll come after you too. Missed payments or default can damage your credit score and put your financial health at risk. That’s why trust is key. If you’re going to co-sign, make sure you have a clear picture of the borrower’s ability to manage payments—and consider monitoring the account to protect yourself. You’re Committed Until They Can Stand Alone Co-signing isn’t temporary by default. Even once the initial mortgage term ends, you won’t automatically be removed. The borrower has to re-qualify on their own, and only then can your name be taken off. If they don’t qualify, you stay on the mortgage for another term. Before agreeing, talk openly about expectations: How long might you be on the mortgage? What’s the plan for eventually removing you? Having these conversations upfront prevents surprises later. It Affects Your Own Borrowing Power When lenders calculate your debt service ratios, the co-signed mortgage counts as your debt—even if you never make a payment on it. This could reduce how much you’re able to borrow in the future, whether it’s for your own home, an investment property, or even refinancing. If you see another mortgage in your future, you’ll want to consider how co-signing could limit your options. The Upside: Helping Someone Get Ahead On the positive side, co-signing can be life-changing for the borrower. You could be helping a family member or friend buy their first home, start building equity, or take an important step forward financially. If handled with clear expectations and trust, it can be a meaningful way to support someone you care about. The Bottom Line Co-signing a mortgage comes with both risks and rewards. It’s not a decision to take lightly, but with careful planning, transparency, and professional advice, it can be done responsibly. If you’re considering co-signing—or want to explore safer alternatives—let’s connect. I’d be happy to walk you through what to expect and help you decide if it’s the right move for you.
Show More